
You have probably met someone who prefers to keep their money in a savings account rather than invest it in the stock market. Or maybe you are one of them.
Though these people understand that the stock market can provide higher returns, they just aren’t ready to stomach the risk that often comes with it. Anyone who has seen what happens during a financial crisis, or even a bear market, can sympathize.
But what if you could invest in the stock market in a way that limits your exposure to market downturns without handling the complexities of derivatives?
That’s the promise of buffer ETFs.
These ETFs protect you against a certain percentage of losses, thereby reducing your exposure to market risk. While they may use complex strategies internally, you can buy them on the stock exchange like any other stock.
But how do buffer ETFs really work, and what is the tradeoff for this downside protection? We answer these and many other relevant questions below.
What are buffer ETFs?
Buffer ETFs, also known as defined-outcome ETFs, are ETFs designed to limit downside risk.
They do this by offering guaranteed protection against a certain percentage of market losses over a given period.
For example, FT Vest U.S. Equity Buffer ETF – November (FNOV) is a buffer ETF that offers protection against “the first 10% of underlying ETF losses” between November 24, 2025, and November 20, 2026.
In other words, as long as market losses don’t exceed 10% within that timeframe, you will never lose money investing in this ETF. Your investment will only start losing money when market losses exceed 10%.
“But doesn’t this constitute a ‘free lunch?’” you ask.
Well, not exactly.
In exchange for downside-risk protection, the ETF caps the gains you can enjoy on the upside. Continuing the example above, FNOV caps upside gains at 16.62% (gross).
Below is a visual image of how buffer ETFs work:
Buffer ETF Example
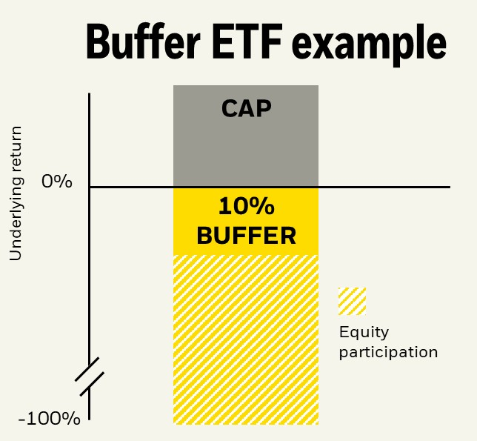
Source: BlackRock
Buffer ETFs track the performance of a broad market index, usually the S&P 500 Index.
With this cap, you can’t participate in the index’s return beyond a certain limit. In other words, even if the S&P 500 Index produced 25% returns between November 24, 2025, and November 20, 2026, investors in FNOV can only enjoy a 16.62% return.
How do buffer ETFs work?
To clarify what buffer ETFs are, let’s look at how they work in practice.
Holdings
Buffer ETFs rely on derivatives to protect investors from downside risk.
As said above, most buffer ETFs track a broad market index like the S&P 500. However, buffer ETFs differ from traditional ETFs because they do not invest in the index’s underlying stocks. Instead, most buffer ETFs invest in Flexible Exchange (FLEX) options, which are exchange-traded option contracts tied to the reference index.
A typical buffer ETF buys put options, which often provide downside protection, and then writes call options, which provide income to finance the puts and cap upside. Some also hold cash, T-bills, and other money-market instruments as collateral.
Outcome period
Buffer ETFs don’t offer the same buffer and upside cap indefinitely. As we saw with FNOV, they have a defined outcome period, usually one year, during which they apply.
Once the outcome period expires, the ETF will reset with a fresh buffer and cap that reflect new market conditions. You can decide to sell at this point or remain invested based on the new terms.
Holding throughout the ETF’s term
The 10% protection and 16.62% upside cap on FNOV apply if you purchased the ETF at the beginning of the outcome period (November 24, 2025) and held it until the end.
This is why buffer ETFs are also known as structured-outcome or defined-outcome ETFs. When you buy them, you have a pre-set return range: the downside protection and the upside cap are clear in advance.
Buying and selling mid-period
When you buy a buffer ETF mid-period, the advertised buffer and cap will not apply in full because the market has shifted since the start of the outcome period.
For most buffer ETFs, you can find the remaining outcome period, upside cap, and buffer (downside protection) on the fund’s homepage. For example, as of this writing, FNOV has 109 days remaining in the outcome period. If you buy now, your upside will be capped at 4.33% (gross), and you will enjoy an 11.11% buffer (gross).
FNOV’s Current Valuation
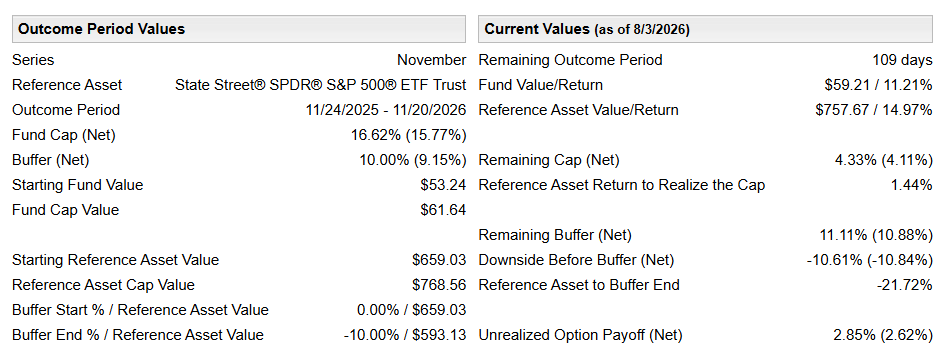
Source: FT Vest
Dividend?
Since buffer ETFs don’t own underlying stocks, they don’t pay dividends.
Put differently, you can only make money through capital appreciation. This happens if you sell at a higher price mid-period or earn the capped return at the end of the outcome period.
What about laddered buffer ETFs?
We saw that buffer ETFs have a defined period during which the buffer and the upside cap apply. If you don’t buy at the beginning of this period, you have to buy mid-period.
Laddered buffer ETFs solve this problem by holding multiple buffer ETFs with staggered reset dates. Like a bond ladder, laddered buffer ETFs provide continuous, rolling protection and upside caps, which makes it unnecessary to time your entry.
For example, FT Vest Laddered Deep Buffer ETF (BUFD) invests in 12 buffer ETFs with different outcome periods. At the time of writing, the remaining outcome period on these ETFs ranges from 18 to 347 days.
This means one underlying ETF resets each month with fresh buffers and caps. At any given period, you will always have exposure to some ETFs early in their period, in the middle of their period, and near the end of their period. This provides smoother protection and more consistent upside over your investment horizon.
Buffer ETFs vs structured notes
Anyone familiar with debt markets has probably noticed similarities between buffer ETFs and structured notes.
Structured notes are debt securities usually issued by banks and other financial institutions.
There are two components of a structured note:
- Bond-like component: This component provides the principal repayment at the note’s maturity. The issuer guarantees the repayment of some or all of the principal, depending on whether it’s a “principal-at-risk” note or a “principal-protected” note.
- Derivative component: This component involves buying options on a stock index, a single stock, commodities, or a basket of securities. While the bond-like component offers principal protection, the derivative component provides upside potential.
Structured notes often mature in one to seven years. Like buffer ETFs, the principal protection comes at the cost of a capped upside. This is often expressed as a participation rate. For example, if a structured note tracking the S&P Index has an 80% participation rate, you will earn only a 24% return when the S&P Index rises by 30%.
What then are the differences between buffer ETFs and structured notes? We consider a few below:
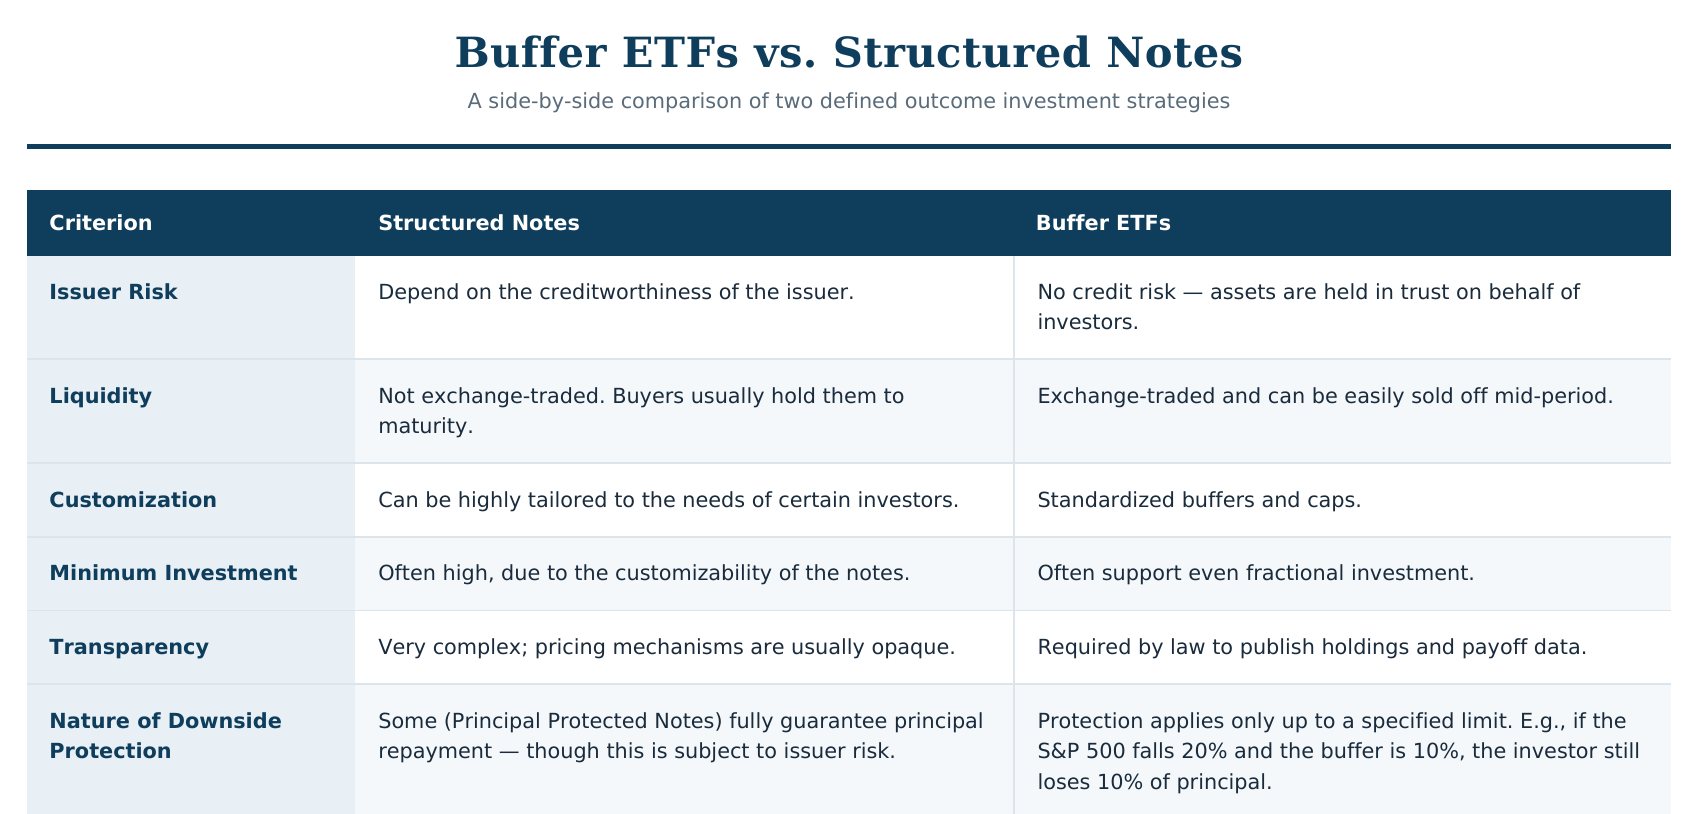
- Issuer risk: Structured notes depend on the issuer’s creditworthiness. Buffer ETFs do not have this credit risk since their assets are held in trust on behalf of investors.
- Liquidity: Structured notes are not exchange-traded. Buyers usually hold them to maturity. Buffer ETFs, by contrast, are exchange-traded and can be easily sold mid-period.
- Customization: As the name implies, structured notes can be highly tailored to specific investors’ needs. In contrast, buffer ETFs have standardized buffers and caps.
- Minimum investment: Due to the customizability of structured notes, they often have high minimum investment requirements. This differs from buffer ETFs, which often support even fractional investment.
- Transparency: Structured notes are very complex, and their pricing mechanisms are usually opaque. By contrast, buffer ETFs are required by law to publish their holdings and payoff data.
- Nature of downside protection: Some structured notes (Principal Protected Notes) completely guarantee principal repayment (though this is subject to issuer risk). In other words, you won’t lose money irrespective of what happens in the market.
In contrast, buffer ETFs offer downside protection only up to a specified limit. If the S&P 500 Index falls by 20% in a given outcome period and your buffer ETF offers only a 10% buffer, you’ll still lose 10% of your principal.
Buffer ETFs vs fixed indexed annuities
Many investors may be unfamiliar with structured notes since they are a niche product. But anyone with some knowledge of retirement planning has probably heard about fixed indexed annuities, or at least of annuities in general.
Fixed indexed annuities are insurance contracts issued by life insurers.
Like some structured notes, they offer full principal protection if held to term. Their gains are generally tied to a stock index, but the index’s return is capped at a given rate or limited by a participation rate.
Fixed indexed annuities are popular with retirement savers, especially those seeking both reasonable income and capital preservation.
Like structured notes, they rely on the insurer’s guarantees, so principal protection depends on the issuer’s solvency.
Below are the differences between buffer ETFs and fixed indexed annuities:
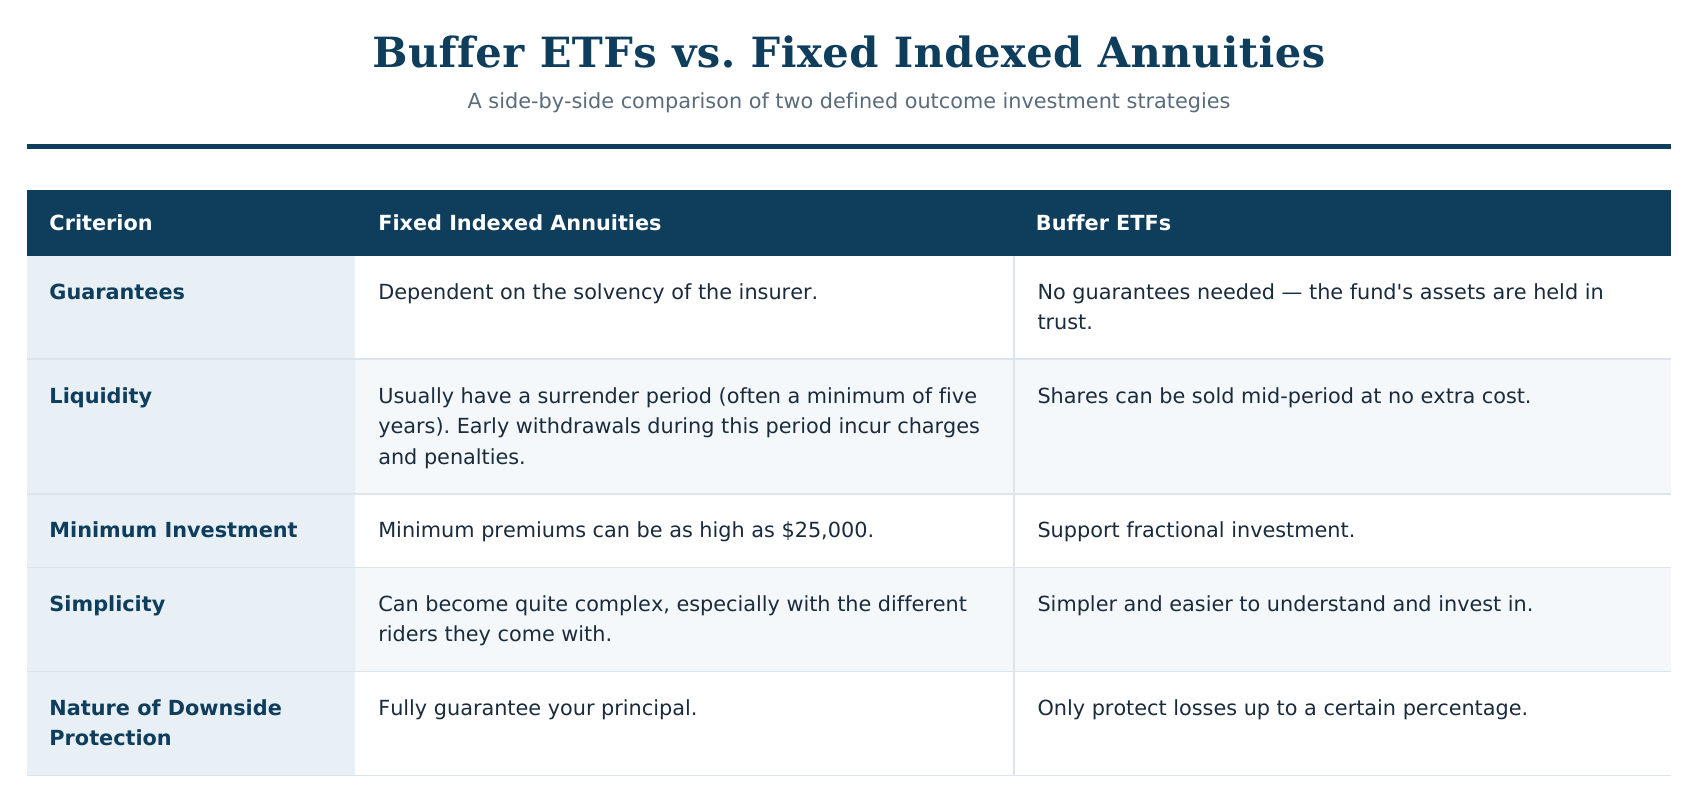
- Guarantees: Fixed indexed annuities depend on the insurer’s solvency. Buffer ETFs do not need guarantees as the fund’s assets are held in trust.
- Liquidity: Fixed indexed annuities usually have a surrender period (often at least five years). Early withdrawals during this surrender period will incur charges and penalties. On the other hand, you can sell shares in a buffer ETF mid-period at no extra cost.
- Minimum investment: Fixed indexed annuities have minimum premiums that can be as high as $25,000. In contrast, buffer ETFs support fractional investment.
- Simplicity: Fixed indexed annuities can become quite complex, especially with the different riders they come with. Buffer ETFs, by contrast, are simpler, easier to understand, and easier to invest in.
- Nature of downside protection: Fixed indexed annuities fully guarantee your principal. Buffer ETFs, by contrast, protect losses only up to a certain percentage.
The growing popularity of buffer ETFs
When market uncertainty and volatility heighten, investors become more concerned about downside protection. Instead of focusing on absolute returns, they shift toward risk-adjusted returns.
In early 2026, market uncertainty and volatility have stemmed from geopolitics and AI disruption, according to BlackRock. For them, despite potential risks, the general macroeconomic environment supports staying invested in equities.
What then is the solution? How do you stay invested in equities while aware of rising uncertainty and volatility?
“During periods of heightened volatility and uncertainty, advisors may consider buffer ETFs to seek greater predictability through the uncertainty of markets,” they noted. “Buffer ETFs can help provide a defined level of downside protection should markets continue to dip, but also can position portfolios for a rebound by capturing market upside up to a cap over a specific outcome period.”
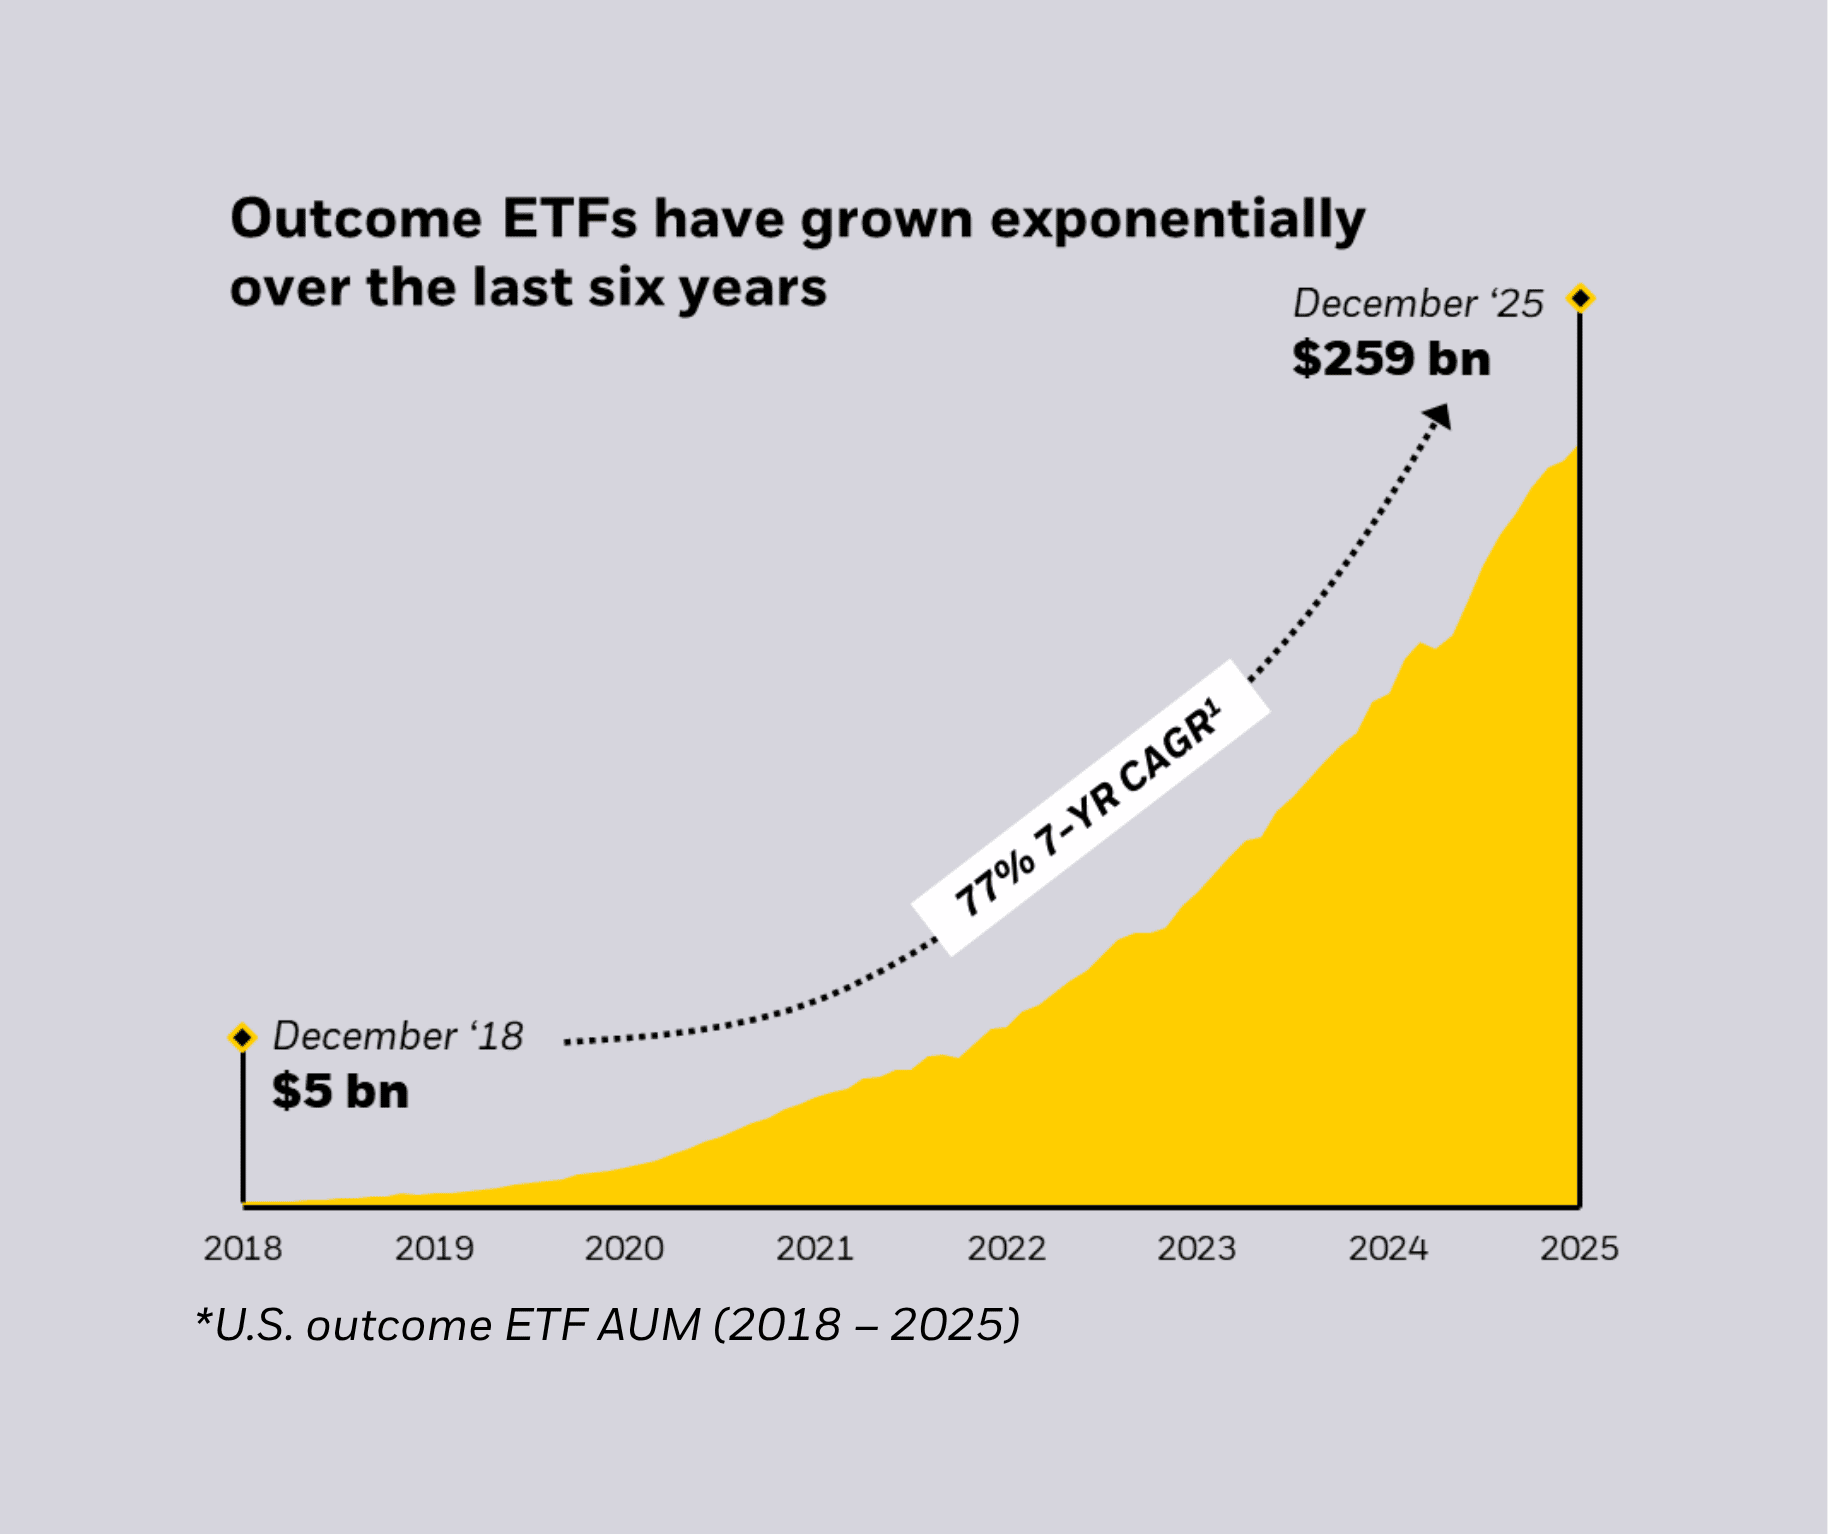
As the chart below shows, outcome (buffer) ETFs in the US grew from $5 billion in assets under management (AUM) in December 2018 to $259 billion, a 77% compounded annual growth rate (CAGR).
Growth of Defined-Outcome ETFs, 2018-2025
Source: BlackRock
Also, buffer ETFs grew 50% year-on-year (YoY) and were one of the fastest-growing ETF segments in 2025, according to BlackRock.
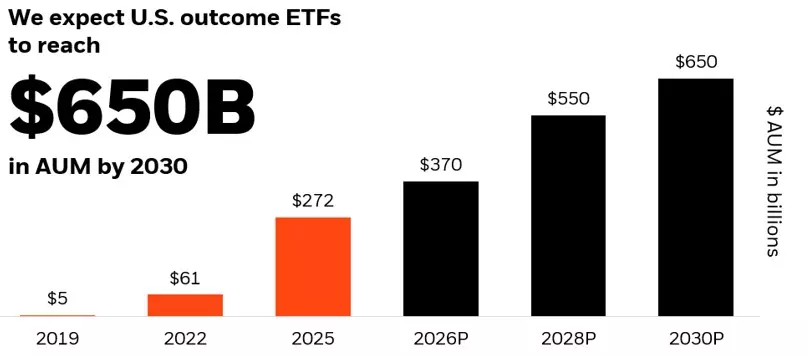
No wonder that at the end of 2025, they projected that outcome ETFs would reach $650 billion in AUM by 2030.
Projected Growth of Outcome ETFs
Source: BlackRock
They expect this growth to be supported by “product innovation, changing demographics and market dynamics.” Also, with 90% of advisors not yet using them as of March, 2025, any surge in advisor interest could lead to rapid adoption.
We can also explore the growth of buffer ETFs in terms of supply.
About 468 structured outcome ETFs traded on US exchanges at the end of November 2025, according to FactSet Insight. More than $1 billion also flowed into these funds that month. Of these, 113 were launched in 2025.
Are buffered ETFs a good investment?
Buffer ETFs have become popular because investors find them valuable for various reasons. We consider some of these below:
- Cushioning volatility amid the weakness of bond-stock portfolios: Investors have typically relied on bond-equity portfolios to enjoy the high returns of the stock market while smoothing out fluctuations and volatility.
However, the correlation between equity and bonds has increased, making bonds less effective as equity diversifiers. “In 2022, as inflation spiked, stocks and bonds fell together – leaving balanced portfolios of 60% equities and 40% bonds with their worst year since 2008,” according to J.P. Morgan.
Consequently, investors need a new source of diversification.
“Investors still want and need equity growth, but it’s increasingly important to have other sources of diversification to cushion volatility,” they continued. “Buffer ETFs are one such tool: they don’t replace fixed income, but they can complement it by reshaping the way equity exposure is experienced.”
- Helping investors stay invested during market downturns: “The average man tends to buy high and sell low,” said Ray Dalio, a legendary investor and founder of Bridgewater Associates, a popular hedge fund.
One reason is that many investors sell during market downturns for fear of losing a significant part of their portfolio. Yet experienced investors have found that time in the market matters more than timing the market, and staying through its highs and lows is often the way to build long-term wealth.
By limiting downside risk, buffer ETFs can give you more confidence to stay in the market and ride out fluctuations instead of selling low to cut losses (and missing the market’s best days later on).
- Enjoying downside risk protection without illiquidity: Structured notes and fixed indexed annuities also provide downside risk protection, but they are illiquid. Buffer ETFs offer similar (though not identical) benefits without the illiquidity.
- Boost capital appreciation for conservative investors: For conservative investors, minimizing risk is the priority. Nevertheless, many low-risk, high-return assets allow them to earn decent returns while achieving that priority – dividend stocks, investment-grade corporate bonds, municipal bonds, etc.
Buffer ETFs also belong on that table. While minimizing downside risk, they provide index-linked returns (even with the cap) that beat savings accounts and fixed-income securities.
Despite these benefits, there are some reasons to be cautious about buffer ETFs:
- Downside protection is not absolute: Unlike structured notes and fixed indexed annuities, you can still lose a portion of your principal if the market falls deeper than the buffer.
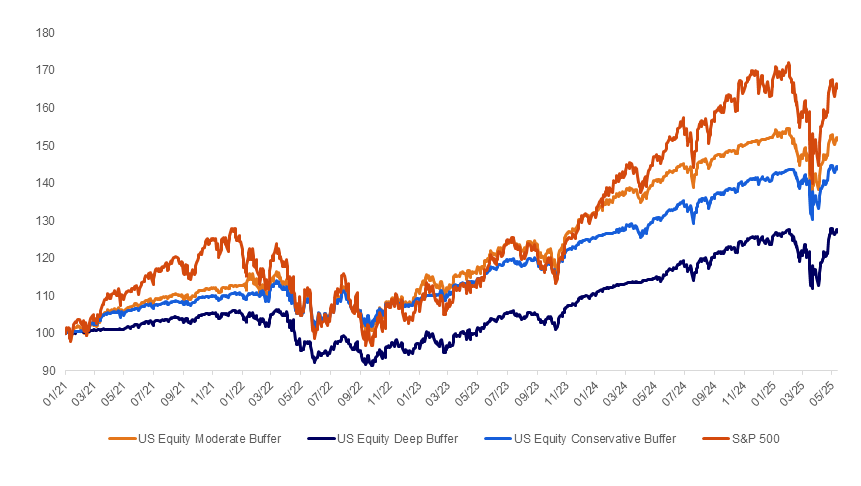
- Lower returns: As seen in the chart below, buffer ETFs tend to underperform the S&P 500 Index:
- The problem of buying mid-period: We have seen that buying a buffer ETF mid-period changes the dynamics, depending on current market conditions. The cap and buffer will differ, and it may be favorable or not.
Buffer ETFs vs. the S&P 500 Index
Source: Russell Investments
But this information may be less relevant if you are a conservative investor more concerned with minimizing risk or investing with peace of mind than maximizing absolute returns.
However, laddered buffer ETFs can solve this problem. These eliminate the need for market timing when purchasing buffer ETFs.
Whether the pros outweigh the cons, or vice versa, depends on your personal situation.
If buffer ETFs interest you, you should talk to your financial advisor about the place they can play (if any) in your portfolio. They’re best positioned to give specific advice based on your time horizon, financial goals, and risk tolerance.
Remember, there is no free lunch, and you should make every portfolio decision with a thorough, contextual evaluation of the pros and cons.
Takeaways
- Buffer ETFs help reduce downside risk. They protect against a predefined level of market losses while letting investors stay invested in equities.
- Protection comes with a tradeoff. In exchange for downside buffers, investors accept a cap on potential upside returns.
- They differ from structured notes and annuities. Buffer ETFs offer greater liquidity, transparency, and lower investment minimums, but they don’t provide full principal protection.
- Demand is growing rapidly. Rising market volatility and investor demand for risk-managed equity exposure have made buffer ETFs one of the fastest-growing ETF categories.
Leave a Reply